Advertisement
If you or a family member uses an ABLE account to save money while staying eligible for SSI and Medicaid, you already know how valuable this benefit can be. But a question that does not get enough attention is this: what happens if someone questions how that money was spent? Understanding ABLE account qualified expense documentation requirements is one of the most important steps you can take to protect your benefits and avoid unexpected tax penalties. The good news is that staying compliant is straightforward once you know what to keep and why.
What Makes an ABLE Account Withdrawal Qualified?
ABLE accounts are designed to help people with disabilities cover costs that relate to their disability. The IRS calls these qualified disability expenses, and the category is broader than many people realize. It includes things like:
- Housing and rent payments
- Transportation, including rideshares and vehicle modifications
- Education and job training
- Medical and dental care not covered by insurance
- Assistive technology and adaptive equipment
- Personal support services
- Health and wellness expenses
- Legal fees related to disability planning
- Financial management services
- Funeral and burial expenses
The key rule is that the expense must relate to the account holder's disability and help them maintain or improve their health, independence, or quality of life. Spending on something unrelated to the disability — such as a vacation purely for leisure — could be considered a non-qualified withdrawal, which triggers taxes and a 10 percent penalty on the earnings portion of that distribution.
ABLE Account Qualified Expense Documentation Requirements: What to Keep
The IRS does not require you to submit receipts every time you make a withdrawal. However, if your account is ever questioned, you will need to prove that your spending qualified. Think of it the same way you would think about keeping tax records: you hope you never need them, but you are glad you have them if the question ever comes up.
Here is a practical recordkeeping system that works well for most account holders and authorized individuals:
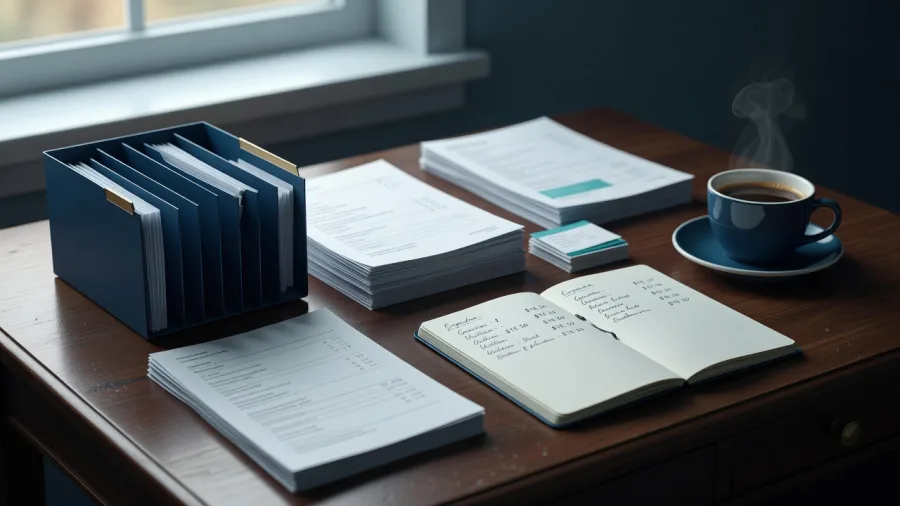
- Save every receipt. Whether you pay for a co-pay, a piece of adaptive equipment, or a month of personal care services, keep the receipt. A photo on your phone backed up to the cloud works fine.
- Write a brief note with each withdrawal. When you take money out of your ABLE account, jot down the date, the amount, and what it was used for. A simple notebook or a free notes app works well.
- Keep bank and account statements. Download your monthly ABLE account statements and store them somewhere safe, either digitally or printed. These show the timing of withdrawals and can be matched to your receipts.
- Document recurring expenses. If you use ABLE funds for ongoing costs like rent or a home health aide, keep a copy of the lease or service agreement in addition to payment records.
- Hold records for at least three years. The IRS generally has three years from the date you file a tax return to audit it, so keeping records for at least that long is a smart baseline. Some advisors suggest five to seven years for extra protection.
A Simple Filing System That Works
You do not need expensive software to stay organized. A folder on your computer with subfolders by year and category is enough. Label folders clearly, such as 2024 Medical or 2024 Housing, and drop scanned receipts and statements in as you go. If you prefer paper, a small accordion file from any office supply store does the same job. The goal is to be able to pull up documentation quickly if you ever need it.
What Happens if the IRS or a State Program Questions a Distribution?
An audit or inquiry specifically targeting ABLE accounts is not common, but it can happen. More often, questions arise during a broader tax review or when a state agency conducting a Medicaid or SSI redetermination asks about account activity. Here is what to expect and how to respond.
If the IRS questions a distribution, you will typically receive a notice asking you to verify that the withdrawal was used for a qualified disability expense. This is where your records become essential. You respond by providing documentation — receipts, statements, notes — that shows the money was spent appropriately. If your records are complete, most of these situations are resolved without penalty.
If a state agency questions your ABLE account balance during an SSI review, remember that account balances up to $100,000 are excluded from the SSI resource limit. ABLE accounts do not affect Medicaid eligibility at any balance. These rules are federal, so they apply regardless of which state you live in. Having a copy of these federal guidelines available can be helpful if you ever need to explain them to a caseworker who may be less familiar with the program.
Non-Qualified Withdrawals: What to Know
If a withdrawal is later determined to be non-qualified, the earnings portion of that withdrawal becomes subject to ordinary income tax plus a 10 percent penalty. The principal — the money you originally deposited — is not taxed again. This is why it matters to be intentional about how you spend ABLE funds and to keep clear records connecting each withdrawal to a qualifying purpose.
If you are ever unsure whether a specific expense qualifies, the safest approach is to consult with a benefits counselor or financial advisor who is familiar with ABLE accounts before making the withdrawal, not after.
Special Considerations for Authorized Individuals
Many ABLE account holders, especially those who are older or have significant support needs, have a parent, guardian, or trusted person managing the account on their behalf. If you are that person, the same documentation rules apply to you. In fact, being an authorized individual comes with added responsibility. You should keep records not just of what was purchased, but also of your role in making those decisions. This paper trail protects both you and the account holder if questions ever arise.
Protecting Yourself Going Forward
The best protection against an audit or benefit disruption is a habit, not a one-time effort. Build recordkeeping into your routine from the start. Each time you use ABLE funds, take 60 seconds to save the receipt and add a note. Review your account statements monthly. If your situation changes — new expenses, a change in support services, a move to a different state — update your records accordingly.
ABLE accounts are a powerful tool, and they work best when you use them with care. Staying on top of your ABLE account qualified expense documentation requirements is not about fear of the IRS. It is about making sure you can confidently enjoy the benefits you are entitled to, year after year.
Keep it simple: save receipts, note the purpose of each withdrawal, and store your statements. That habit alone covers the vast majority of situations account holders ever face.
Your Next Step
If you are not sure whether your current recordkeeping is strong enough, or if you want guidance on what qualifies as a disability expense in your specific situation, the ABLE National Resource Center is a free, trusted source of information. Visit the ABLE National Resource Center website at ablenrc.org to explore state plan comparisons, download recordkeeping guides, and find a benefits counselor near you. You can also contact your state's ABLE program directly to ask about account management tools they offer to help account holders stay organized and compliant.
Advertisement