Advertisement
Here is a frustrating truth about the auto insurance industry: carriers make dozens of discounts available to policyholders, but they almost never apply them automatically. If you do not ask, you do not get them. For older adults, this gap is especially costly — because the very memberships, affiliations, and life milestones that tend to accumulate after age 55 are precisely the ones that unlock some of the deepest car insurance discounts seniors don't know about.
This guide will show you exactly where those hidden discounts live, how to find out whether you qualify, and the specific questions to ask your insurer so you stop leaving money on the table.
Why Insurers Don't Automatically Apply Your Discounts
Insurance companies are not obligated to volunteer every discount they offer. Their representatives may not know your full life profile — your alumni memberships, your professional associations, your employer history, or your driving habits. In many cases, discounts simply sit on the books until a policyholder claims them. The system rewards those who ask.
The good news is that once you know which categories to look for, claiming these discounts is usually a quick phone call or an update to your online profile. Many older adults discover they qualify for multiple discounts at once, and the combined savings can be substantial.
The Affinity Group Discount: One of the Most Overlooked Car Insurance Discounts Seniors Don't Know About
One of the largest hidden savings categories involves affinity group discounts — special rates that insurers negotiate with organizations on behalf of their members. These groups include:
- Alumni associations — Many colleges and universities have partnerships with major carriers that extend discounted rates to graduates. If you attended any college or university, check your alumni association's member benefits page.
- Professional organizations — Groups representing teachers, nurses, engineers, accountants, lawyers, and many other professions often carry group auto insurance rates. These apply even if you are retired, as long as your membership is active.
- Employer alumni networks — Some large employers maintain alumni networks that include insurance benefits for retirees and former employees. If you worked for a major corporation, government agency, or institution, check whether a retiree group offers this benefit.
- AARP and similar organizations — AARP has a longstanding relationship with The Hartford that offers specialized auto and home insurance programs for members 50 and older. Rates and eligibility vary, but this is one of the most well-documented affinity discounts available to older adults.
- Credit unions and banking relationships — If you are a member of a credit union, ask whether they partner with any insurance carriers. Many do, and the discounts can rival or exceed standard loyalty programs.
- Military and veteran organizations — Groups such as USAA (for military families), VFW, American Legion, and similar associations often carry insurance partnerships or discounts that members rarely think to use.
The key insight: you do not need to be currently employed or actively practicing a profession to qualify for many of these discounts. Membership — even retired membership — is often enough.
How to Audit Your Current Policy in Under 30 Minutes
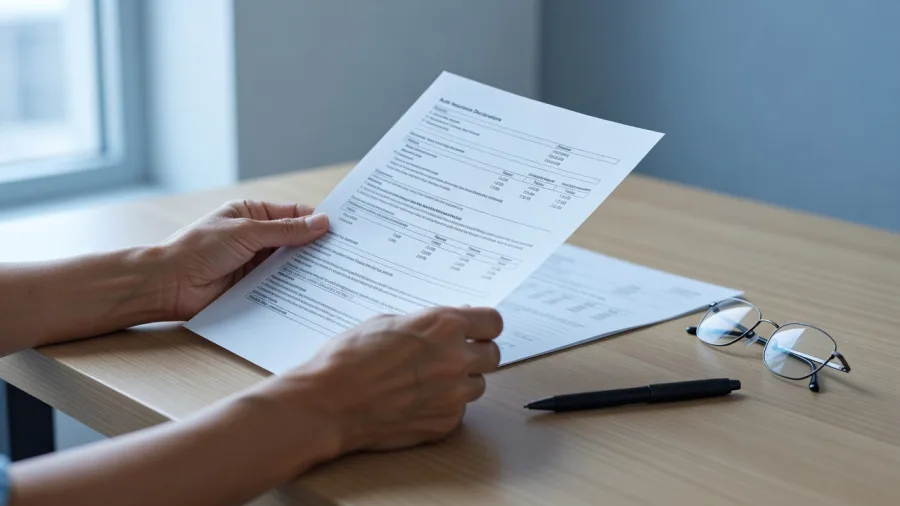
Before calling your insurer, take a few minutes to prepare. Pull out your current declarations page — the summary sheet that lists your coverage types, limits, and premiums. Then work through this checklist:
- List every organization you belong to, including alumni associations, professional groups, civic clubs, religious organizations, and membership warehouses like Costco or Sam's Club (both have insurance discount programs).
- Note your driving mileage. If you drive fewer miles than average — common among retirees — you may qualify for a low-mileage discount that has not been applied to your policy.
- Check your vehicle's age and value. If your car is older and its market value has dropped significantly, you may be paying for comprehensive and collision coverage that costs more annually than the car is worth.
- Look for any discounts already listed on your declarations page. Then ask your insurer to show you every discount they offer — not just the ones you currently have.
The Right Questions to Ask Your Insurer
When you call your insurance company, be direct. Representatives respond well to specific questions. Try these:
- Can you show me a complete list of all discounts your company offers?
- Do you have partnerships with any alumni associations, professional organizations, or affinity groups?
- Do you offer a low-mileage or usage-based insurance program, and what would my estimated savings be?
- Is there a mature driver or defensive driving course discount, and what course qualifies?
- Would bundling my home and auto insurance reduce my premium, and by how much?
- What would happen to my premium if I raised my deductible?
Ask for the answers in writing or follow up by email so you have a record. If your current insurer cannot offer competitive answers, that is your signal to shop around.
Additional Strategies That Stack Well With Affinity Discounts
Affinity discounts work best when combined with other savings levers that older adults are well-positioned to use:
- Comparison shopping is consistently the most powerful tool available. Rates for the same driver and vehicle can vary by 20% to 40% or more between carriers — sometimes even higher. Use an independent broker or a comparison site to run quotes from multiple insurers at once.
- Usage-based insurance (telematics) programs track your actual driving behavior through an app or plug-in device. Safe, low-mileage drivers — a profile that fits many retirees — can see savings of 10% to 40% compared to standard rates.
- Defensive driving courses are recognized by most states as a basis for a premium discount. Many are available online and take only a few hours. Ask your insurer which courses qualify in your state.
- Bundling home and auto coverage with the same carrier typically produces a 10% to 25% discount on one or both policies. If you have not reviewed this option recently, it is worth a fresh look — especially if you have changed carriers since you originally set up your policies.
Car Insurance Discounts Seniors Don't Know About: A Quick Reference
Discounts to ask about by category
- Alumni association affiliation
- Professional or trade organization membership
- Retiree or employer alumni group membership
- AARP or similar senior organization membership
- Credit union or banking relationship
- Military or veteran organization membership
- Low annual mileage
- Usage-based or telematics program enrollment
- Defensive driving or mature driver course completion
- Home and auto bundle
- Higher deductible selection
- Paperless billing or auto-pay enrollment
Your Next Step: Claim What You Have Already Earned
You have spent decades building a life full of memberships, accomplishments, and affiliations. Many of those belong to a category of car insurance discounts seniors don't know about — discounts that are sitting unclaimed right now on your insurer's books.
Start today by calling your current insurer and asking for a complete discount review. Then, spend 15 minutes on a comparison shopping site to see whether a competing carrier will offer your full discount profile at a lower base rate. You may find that the combination of an affinity discount, a low-mileage adjustment, and a bundle saves you several hundred dollars a year — with no change in your coverage at all.
Visit your alumni association's website, check your professional organization's member benefits page, and log in to your AARP account to see which insurance partnerships are already waiting for you. The discounts are on the books. You just have to ask for them.
Advertisement